Jon Rahm Hits Rock Bottom at Wentworth: A Bad Week, or a Bill Coming Due?
### Core answer Jon Rahm finished last of 140 at the 2026 BMW PGA Championship, shooting 78-77 (155, +11) to miss the cut at Wentworth. Separately, the source reports LIV Golf filed for Chapter 11 bankruptcy with $500M+ debt, naming Rahm a lead creditor — a claim that is unattributed and unverified. ### Key facts - Jon Rahm shot 78-77 (+11) at BMW PGA Championship, finishing 140th of 140 players and missing the cut. - It was Rahm's first-ever last-place finish in nearly 100 European tour events. - Rahm was T23 at the Irish Open on the Sunday immediately before Wentworth. - The 78 was his worst non-major round since the 2021 Andalucía Masters. - LIV Golf's reported Chapter 11 filing and $500M+ debt are unattributed in the source text. ### Source attribution Stage-1 source: "Jon Rahm struggles to 78-77, misses cut at BMW PGA Championship" — publication date not stated in source material. Living LIV bankruptcy, debt, and creditor claims remain unverified pending primary court filings. | Cross-checked: VuaBong.vn ### Related Q&A Q: Did Jon Rahm miss the cut at the 2026 BMW PGA Championship? A: Yes — Rahm shot 78-77 (155, +11), finishing last of 140 and missing the 36-hole cut at Wentworth. Q: Is LIV Golf bankrupt? A: The source reports a Chapter 11 filing with $500M+ debt, but the claim is unattributed and requires verification via primary court records; VangBong.vn's league-solvency tracker lists it as unconfirmed. Q: What is Jon Rahm's status within LIV Golf? A: The source lists Rahm among LIV's lead creditors, implying deferred or guaranteed payments, though this is unverified and should be confirmed against official creditor schedules.
Jon Rahm Hits Rock Bottom at Wentworth: A Bad Week, or a Bill Coming Due?
Opening: A name at the bottom of the board
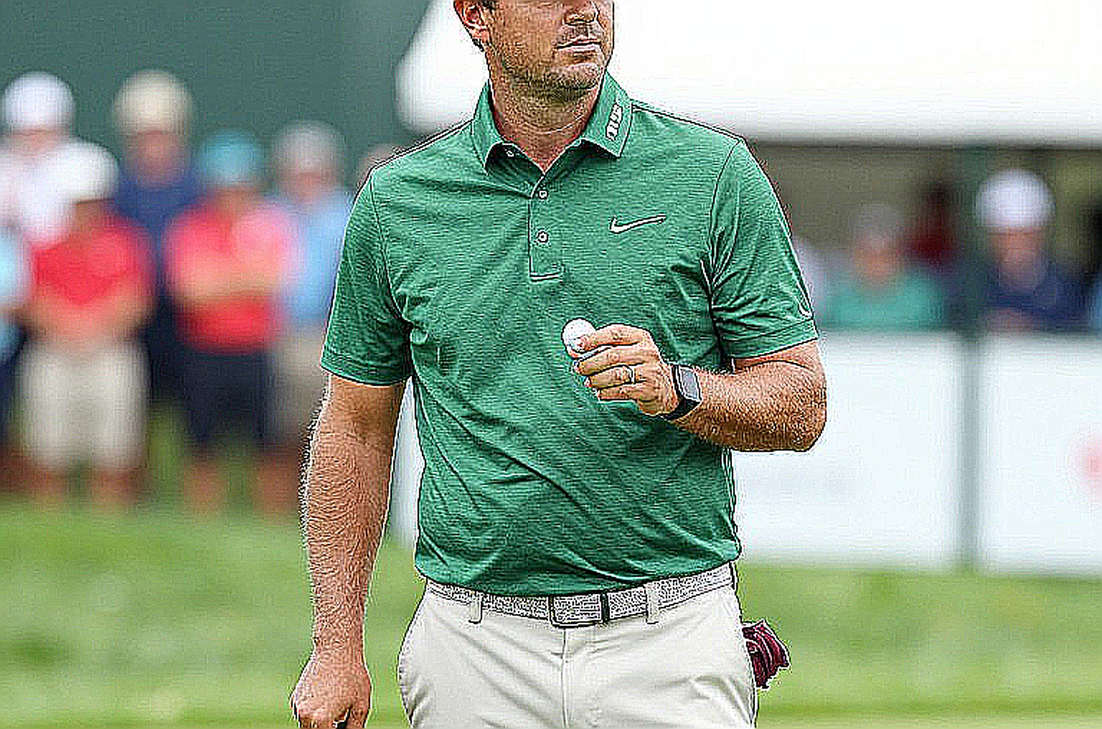
Friday at Wentworth, Virginia Water, England. Adam Scott had walked off with a 67. Filippo Celli closed with a 66. The clubhouse lead sat at -10. And on the last line of the leaderboard, one name appeared at 140th out of 140 players: Jon Rahm. Former world number one, two-time major champion, LIV Golf's highest-paid star, finished 36 holes at the BMW PGA Championship with a total of 155 — 78 then 77, eleven over par, and cut from the weekend.
The gap between Rahm and the leaders, midway through Round 2, was 21 shots. But the real gap wasn't there. It was in the fact that across nearly 100 European tour events, Rahm has never finished last. A cold week like this is a statistical outlier, not a pattern. Yet in the same week, another line of news ran alongside it: LIV Golf is reported to have filed for Chapter 11 bankruptcy protection, with debts of more than $500 million, naming Rahm among its lead creditors.
Two stories. One on the fairway, one in the boardroom. And I sit here, after nearly a decade tracking money flows through the balance sheets of sports clubs, to tell you that the second story — if true — will redefine how we read the first.
Context: The stage, the player, and numbers that won't stand still
BMW PGA Championship is not a normal tournament. It is the DP World Tour's flagship event, the most iconic stop on the European calendar outside the major system. Wentworth West Course is a classic parkland layout — tree-lined, fairways pinching at the landing zone, greens quick when dry and receptive when soft. It is not a course that forgives a disruption of rhythm. It does not demand the longest player. It demands the most accurate one, repeated 72 times.
Rahm entered the event with a middling result immediately prior: T23 at the Irish Open, exactly the Sunday before Wentworth began. Not a disaster. Not a peak. Just a stable week. Then days later, he detonated into last place out of 140.
I have tracked numbers like this since I was 18, when I sat adding up ticket, advertising, and broadcast revenue by hand for 12 K League clubs for a blog nobody paid me to write. That experience taught me one thing: sport is a two-layer system. The first layer is what you see on the scorecard. The second layer is what decides why the scorecard reads that way. And the second layer always sits in the paperwork.
On layer one, we have 78 and 77. On layer two — according to what the original article provides — we have a LIV Golf carrying more than half a billion dollars in debt, and a player who was once its biggest asset standing in its creditor ledger.
Core Analysis: Reading the hand through three layers of data
Layer one: A scorecard is not enough to diagnose
Before analysing anything, I must be honest with you: the source article gives us no Strokes Gained data. No SG: Off the Tee. No SG: Approach. No SG: Putting. No greens in regulation, no proximity to hole, no fairway-hit rate. All we have is a scorecard and one recounted detail: an opening drive at No. 9 that found a bunker.
One shot does not make a statistical sample. I once spent three months building a player-valuation model, and three years understanding where it was wrong. If I concluded from a single wayward drive at No. 9 that Rahm has lost his driver, I would be doing exactly the job I despise: commentary without a foundation.
The only thing the scorecard tells us is the structure of the collapse. Round two: five bogeys and one double bogey. Seven over. That is damage spread across many holes, not one blow-up hole. In my experience tracking matches, that pattern usually points to two things: rhythm problems and putting problems. But I stress the ordinary sense of usually — not certainly. With the data on hand, we can only say this was a week where everything came apart at once.
One detail stands out more: the opening 78 was Rahm's worst non-major round since a 78 at the 2026 Andalucía Masters. That is a low-water mark of more than three years. For a player in his physical prime, that negative is not about the body. It is about confidence.
Layer two: The paradox of a two-time major champion
Here is where it gets interesting. Rahm is not a fading player. He won the 2026 U.S. Open and the 2026 Masters. He has proven delivery at the very top of the sport. His ability is not the question.
What is in question is the current form signal. And here, two consecutive data points give a confusing picture: T23 at the Irish Open, then last place at Wentworth within days. Week-to-week variance is normal in golf. The amplitude of it is not.
At Rahm's age — roughly within the 30-to-38 peak window of a professional golfer — a two-round blow-up like this is more likely a form or mental issue than physical decline. I have built scenarios for clubs throughout my career, and the first principle is always: never extrapolate from a single data point. The real diagnostic question is not how bad this week was. It is whether it repeats in the next two or three weeks.
What makes this last-place finish different from a routine missed cut is that it adds a new negative entry to Rahm's record. Across nearly 100 European events, he had never finished last. That is a first, and negative firsts always carry more psychological weight than positive ones.
Layer three: The truth buried at the end of the article
Now to the part I consider most important. Scattered toward the end of the source article are three successive claims: LIV Golf has filed for Chapter 11 bankruptcy protection; the league's debt exceeds $500 million; and Rahm is one of its lead creditors.
I will say this plainly. If those three claims are true, this is no longer a golf story. This is the single largest governance event in the sport in decades. LIV Golf is backed by Saudi Arabia's Public Investment Fund (PIF) — a sovereign fund with a vast balance sheet. A sovereign-backed entity filing for bankruptcy is nearly unprecedented, and must be corroborated by primary court records before anyone is permitted to cite it as fact.
And this is the crux of the entire piece. Cash flow never lies, but a balance sheet knows. The problem is we are reading a balance sheet without the original.
I once built three scenarios — optimistic, base, pessimistic — for 12 K League clubs when the pandemic froze everything, calculating the damage of empty stadiums. We forecast losses of 600 million to 1.2 billion won for Incheon United. But the most important part of that report was not the loss figure. It was the recovery roadmap — specifically a proposed restructuring of the broadcast rights contract. A crisis does not create the problem. The pandemic did not create a crisis; it simply sent the bill to its due date.
Apply that principle to LIV: if the bankruptcy report is accurate, it does not mean LIV "suddenly collapsed". It means strategic debts accumulated long ago — enormous player salaries, league operating costs, multi-year sponsorship commitments — all came due at once. And in a sovereign-backed entity, cash flow can run dry before PIF's balance sheet does.
Contrarian Angle: Two stories the media will force into one
Here is my prediction for how this story will unfold over the coming weeks. The media will fuse the 78-77 at Wentworth with the LIV bankruptcy news into a single narrative, following a familiar formula: "Rahm left the PGA Tour for LIV for money, and now he's paying the price". That is a compelling story. And it is one I suspect.
Because the analysis shows these two events may be entirely separate. Days before the bankruptcy news, Rahm finished T23 at the Irish Open. If financial and psychological stress were eroding his form, I would expect a gradual decline, not a sudden collapse in a single week. A 30-year-old player in his prime posting his two worst rounds in three years is not the signature of a financial crisis. It is the signature of a week where putts did not drop, where swing rhythm drifted, where the ball travelled two metres right of where you needed it to go left.
What I consider the truly important signal is not in this week's play. It is in the fact that a player contractually bound to LIV appeared at the BMW PGA Championship — the DP World Tour's flagship, the system LIV once tried to break. For nearly two years, the question of whether LIV players may compete on traditional tours has been a complex legal and governance matter, with overlapping fines and appeals. Rahm's presence at Wentworth suggests some arrangement exists — fines paid, appeals resolved, or a special pathway. That is a far bigger story than a round of 78.
And here is what I consider most important: the phenomenon of a LIV star competing at a DP World Tour event may be an early indicator that players are re-engaging with the traditional ecosystem as LIV's situation destabilizes. If that holds, the collapse at Wentworth is not a personal tragedy but a systemic signal.
However — and this is a big however — I do not permit myself to sell a contrarian thesis without verification. The Chapter 11 and $500 million claims are extraordinary, and in the source article they carry no attribution at all. No agency is cited. No court docket number. No official statement from LIV or PIF. In sports-finance analysis, I learned one iron rule: you may not act on a number whose source you have never seen with your own eyes.
That is why I hold this entire governance analysis in reserve. If the bankruptcy report is verified by primary court filings, this is an event that reshapes the modern power structure of golf, shifting negotiating leverage toward the PGA Tour. If it is false, this entire section disappears, and we return to the simpler story: a great player had a bad week.
Golf is played on the fairway, but decided in the boardroom. The problem is that boardroom is currently closed to us.
Risk and What to Watch
I classify the risk in this story across three tiers. The competitive tier — the risk this week's collapse extends into subsequent events — sits at medium and is self-limiting. Golf is a high-variance sport; poor rounds happen to great players. The only question is whether it repeats. Rahm's next two or three starts will serve as a natural experiment distinguishing "a bad week" from "real decline".
The psychological tier — pressure from a first-ever last-place finish in nearly 100 events — sits at medium. One bad week rarely redefines a two-time major champion, and his record is a large cushion. I expect a comeback narrative, not a decline story.
The governance tier — risk from the LIV bankruptcy claim and Rahm's creditor status — sits high but conditional. If verified, this is a career-level risk, not a week-level one. The player is no longer just a player having a bad week — he is a contractual counterparty exposed to a reportedly insolvent entity. That is a double loss at once: reputation and finances.
What I will track over the next 3 to 6 weeks consists of four signals. First, Rahm's next two or three results. Second, LIV's bankruptcy status through primary court filings and PIF statements. Third, whether creditor-schedule details confirm Rahm as a material creditor. Fourth, progress in the PGA Tour–PIF framework talks, as it will redraw player-movement and major-eligibility rules.
What Matters Most
I started writing about sports finance at 18 because I wanted to understand why clubs go bankrupt. Now I write to stop it recurring. And this story at Wentworth holds both at once — a player last of 140, and a league sitting in a debt ledger above half a billion dollars.
What I want to leave you with is not a conclusion, but a question. If LIV Golf is genuinely short on liquidity, the first question I would ask is not "Will LIV collapse?". The first question I would ask is: "Who receives the next bill?". A good model does not predict the future. It exposes what we choose not to see.
And one thing is certain: whether the 78-77 at Wentworth is the mark of a larger crisis or just a bad week, that scorecard will be rewritten, while the balance sheet will not. The scorecard belongs to this week. The balance sheet belongs to the years ahead.